
‘…the more his body sank into it the more water ran out over the tub’: Vitruvius, De Architectura, Book IX
When King Hiero II of Syracuse suspected that his new crown was not made of pure gold, he turned to Archimedes. Pondering the King’s suspicions, Archimedes stepped into a bath. It proved to be his Eureka moment: as he submerged himself, the rising water revealed the principle of displacement.
Credit markets may now be experiencing their own Archimedean moment.
Hyperscalers are investing heavily in data centres, chips and power to build their AI capabilities and are increasingly turning to debt markets to fund it.
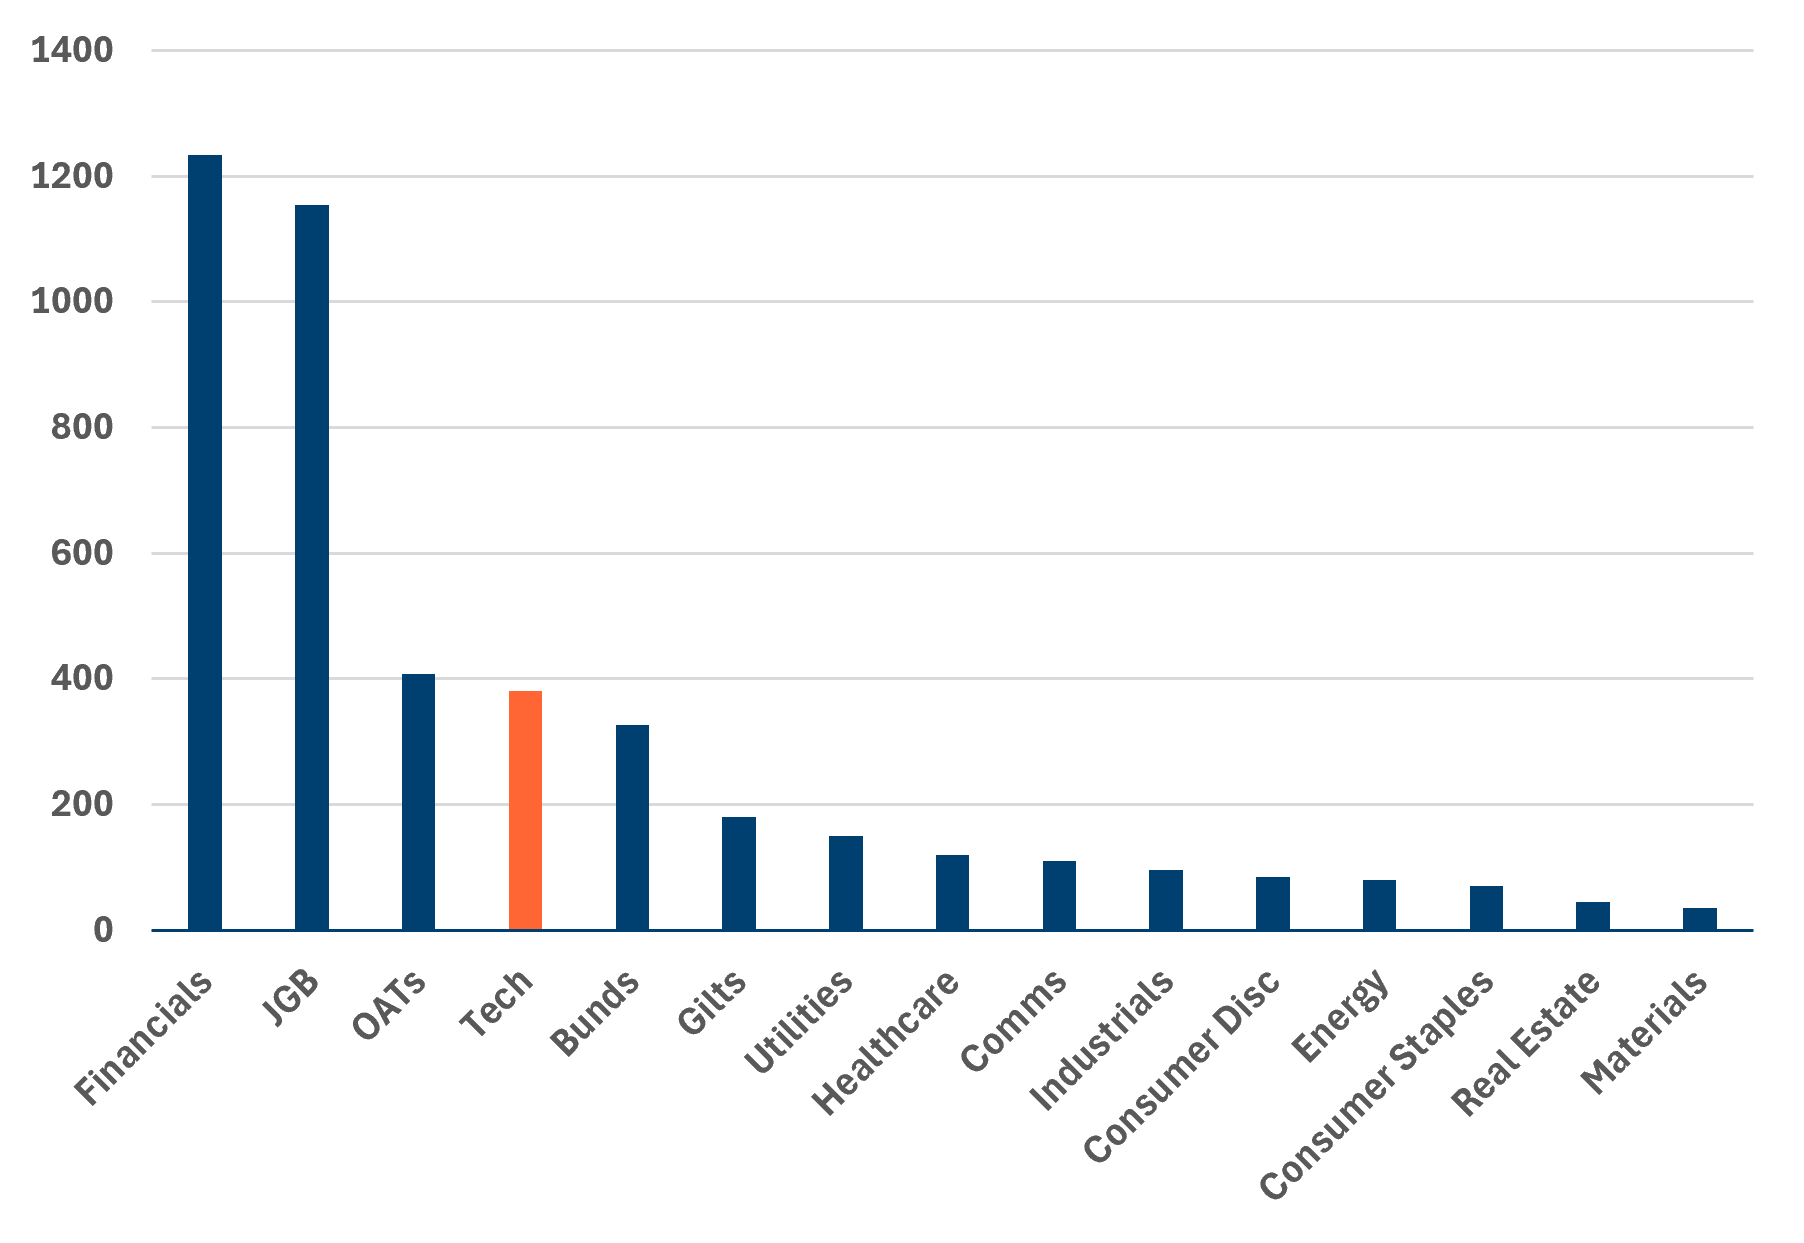
How much debt are we talking about? A lot. AI-related bond issuance reached $380.5bn as of mid-August 20261. This is comparable in scale to sovereign issuance from France and Germany year-to-date and double that of the UK (see the chart below).
Expectations also continue to be revised higher. JP Morgan and Barclays have both recently increased their 2026 AI-related issuance forecasts by 20%, with the former citing seven potential investment-grade data centre financings, four of which are associated with Oracle and OpenAI. As reported by Bloomberg, banks are lining up another $15bn for an Anthropic data centre project in Texas, backstopped by Google. Bank of America, meanwhile, estimates that dollar-denominated investment grade hyperscaler debt issuance could total $371bn across 2026 and 2027.
Is this the total financing picture? No. Public bond issuance only captures part of it. Goldman Sachs estimates that hyperscalers have $1.5trn of aggregate lease commitments, of which $1trn relates to leases that have not yet started, and so does not appear on balance sheets.
Meta Platforms (Meta)’s Hyperion data centre is an example. A joint venture with Blue Owl issued $27bn of debt against Meta’s commitment to lease the facility for at least 20 years. Therefore, although the debt sits outside Meta’s balance sheet, the company is still liable for the lease payments.
Why is issuance rising? The potential of AI is turning traditionally asset-light businesses into increasingly capital-intensive ones, and that infrastructure needs financing.
Does this imply financial stress? No. Hyperscalers remain some of the strongest credit-rated businesses as Morgan Stanley, for example, estimates their average on-balance sheet net leverage at only 0.5x, against 1.8x for US non-financial companies.
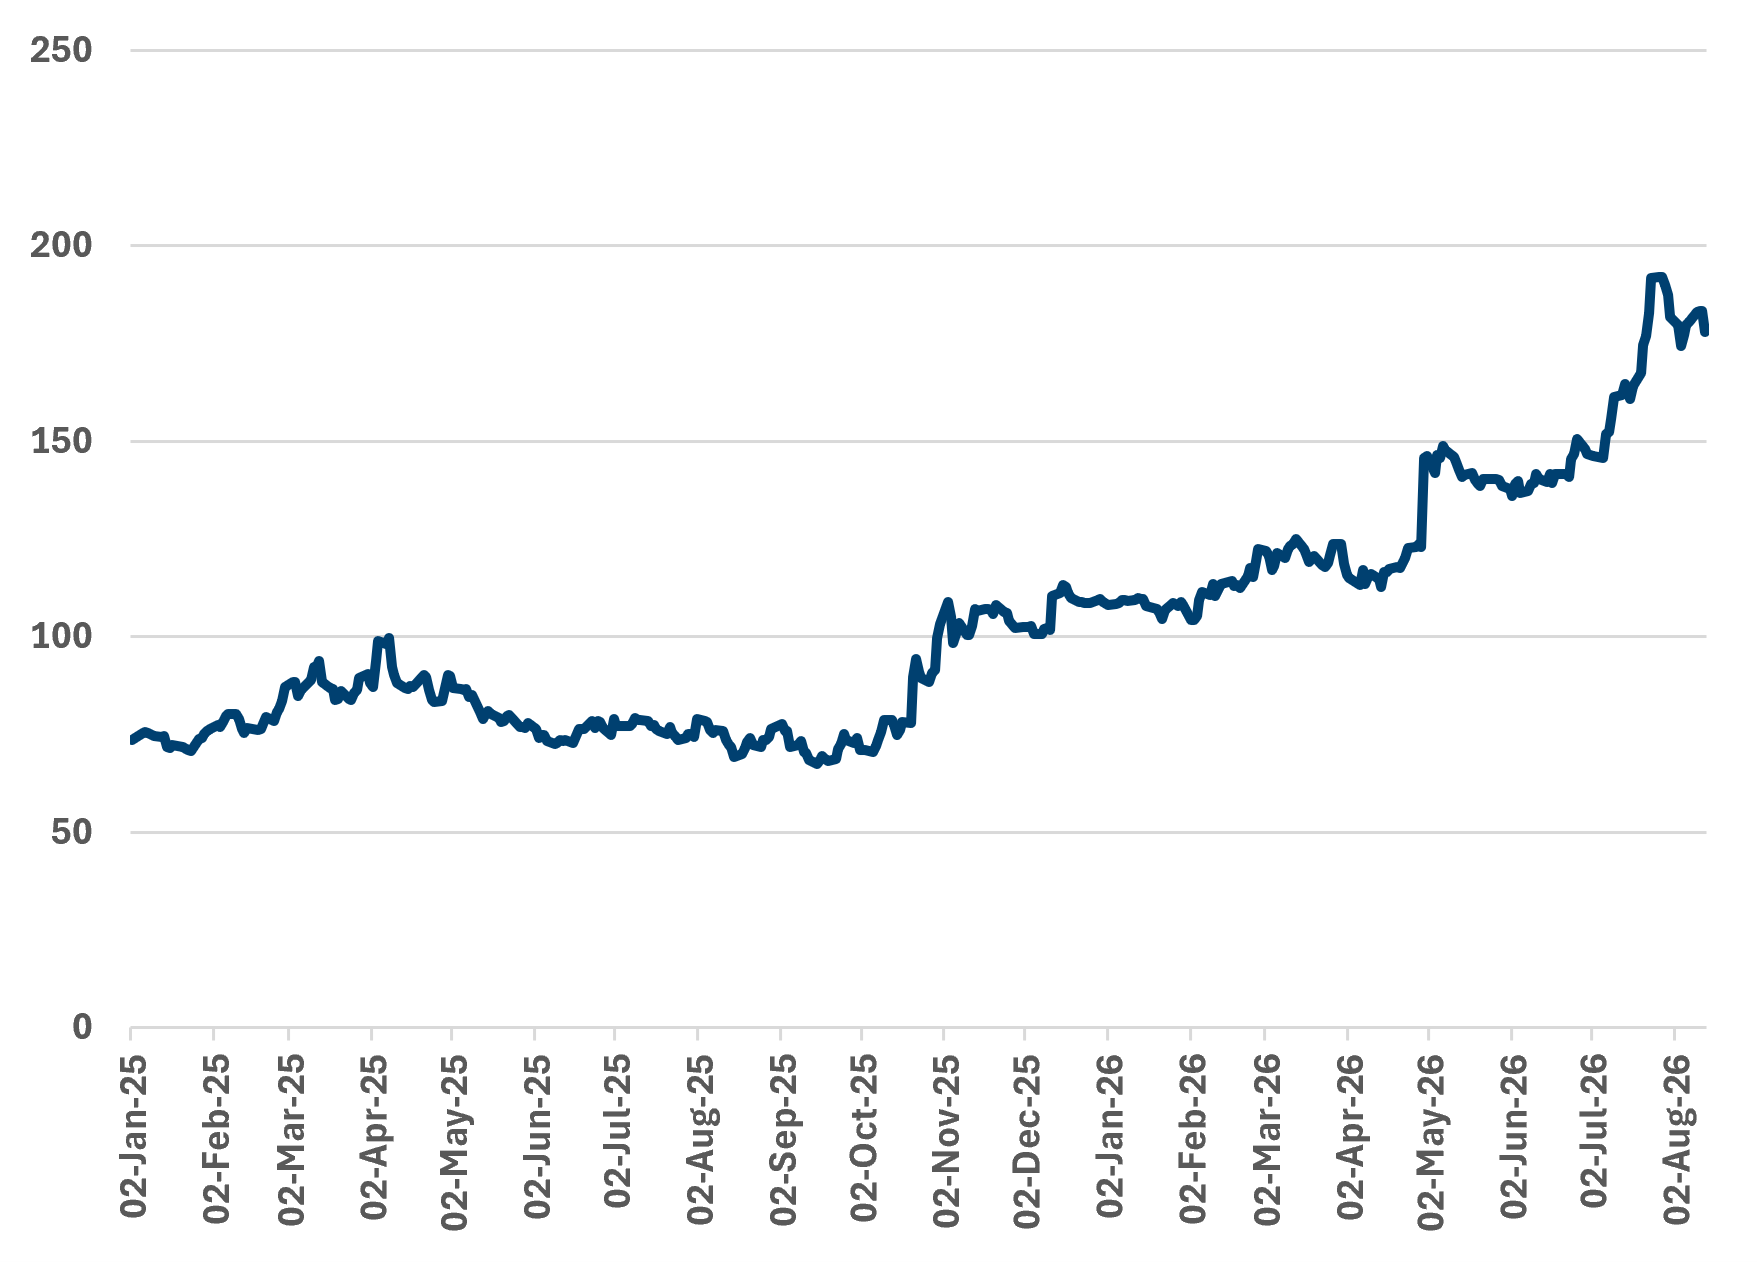
However, the market’s ability to absorb the increase in supply is being tested. Bid-to-cover ratios for new AI-related issuance have fallen from 5x in February this year to below 2x by July, while Amazon’s $25bn July transaction also required an 18-21bps yield sweetener after orders proved softer than expected.
Year-to-date 2026 bond issuance ($bn) AI-related vs sovereigns vs index-linked gifts | Hyperscaler credit spreads (bps) (Jan 2025 - Aug 2026) |
 |  |
| Source: Polar Capital, Bloomberg, August 2026 |
So, is this a fundamental concern for corporate bond markets? No, but the ‘spread fatigue’ created by such sizeable tech-related bond issuance (see the chart above) can push borrowing costs wider for the broader market as it struggles to absorb the supply.
This is Archimedes’ principle in action. With finite investor capital and hundreds of billions of dollars of investment grade tech debt entering the market, other sectors must compete for that capital. The result is displacement.
Could financial credit spreads widen as a result? Possibly. According to Bloomberg, financials account for 40% of the investment grade corporate bond universe and are unlikely to be immune from a broader repricing of credit. That said, technically driven widening could represent a buying opportunity.
Why would we buy the widening? Financial fundamentals remain resilient. The European Banking Authority's Risk Assessment Report in June shows capital ratios near record highs, with 500bps of headroom above minimum requirements. Asset quality is also solid, with low non-performing loans and de minimis private credit exposure.
Recent stress tests tell a similar story. Under the Federal Reserve's 2026 scenario (unemployment at 10%, commercial real estate falling 39%, and house prices declining 30%), all participants passed, despite a hypothetical $708bn of losses. The five participating European banks also experienced lower capital drawdowns than in previous years.
Conclusion
To summarise, the unprecedented financing needs of AI could push spreads wider in other parts of the credit market. If financial credit spreads widen as a result, without a corresponding deterioration in fundamentals, we would view that displacement as an opportunity to add risk.
1 Source: Bloomberg’s theme assessment of AI-linked securities.